A currency can look like a remote concern until it starts shaking the furniture in everyone else’s house. The Japanese yen is one of those currencies. A sharp move in Tokyo can ricochet through US Treasury markets, emerging-market assets, European exporters and the holiday budget of anyone choosing between Tokyo and Tuscany.
That reach is not a mystery, even if currency markets often make a fog machine look transparent. Japan has spent years with exceptionally low interest rates, turning the yen into a cheap source of funding for investors worldwide. At the same time, Japan is a major overseas investor and a significant holder of foreign bonds. When the yen moves abruptly, those two roles can collide—with consequences far beyond Japan’s shores.
The Bank of Japan’s delicate rate puzzle
The starting point is monetary policy. When Japan’s interest rates sit well below those in the United States or other major economies, investors have a clear incentive to sell or borrow yen and place money in assets offering higher returns elsewhere. That persistent outflow can put downward pressure on the Japanese currency.
A weaker yen has obvious winners. Japanese exporters receive more yen when overseas earnings are converted back home, which can flatter profits at internationally active companies. Foreign visitors also find Japan cheaper on arrival: hotel rooms, restaurant bills and retail purchases suddenly feel less punishing. Tokyo’s packed shopping districts are a very visible illustration of exchange-rate economics at work.
But the bargain has a bill. Japan relies heavily on imported energy and other goods. When the currency weakens, those imports cost more in yen, feeding into household bills and the broader cost of living. That creates an awkward political and economic choice for the Bank of Japan: raise rates too little and import-price pressure persists; raise them too quickly and fragile domestic growth risks being flattened by the monetary-policy steamroller.
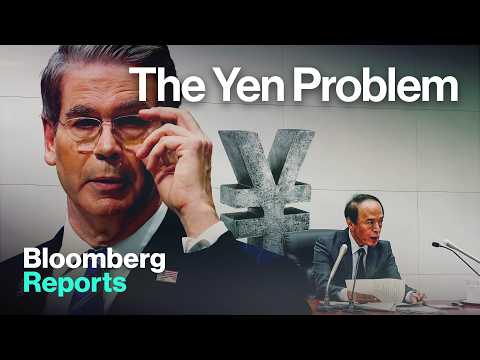
The reference video highlights this tension, describing the yen at levels against the dollar not seen for decades and linking the weakness to Japan’s low-rate environment. Whether markets are focused on a specific exchange-rate level or the next policy meeting, the essential point is the same: small shifts in expectations for Japanese rates can trigger very large moves in capital.
The carry trade: cheap yen, expensive unwinds
The phrase “carry trade” sounds like something involving luggage and an airport surcharge. In finance, it means borrowing in a low-yielding currency and investing the proceeds in assets with higher yields. The hoped-for profit comes from the gap between borrowing costs and investment returns.
For years, the yen has been one of the world’s favourite funding currencies. Investors have used it to finance positions in US bonds, equities and higher-yielding markets including countries such as Brazil and Mexico. This can provide a substantial, if largely invisible, stream of liquidity to global markets.
The trouble arrives when the trade reverses. If the yen strengthens rapidly—or investors expect Japanese rates to rise—the cost of repaying yen borrowing increases. Traders may rush to close positions, selling assets elsewhere to buy yen back. That can turn an apparently local currency move into a broad market retreat. It is the financial equivalent of discovering that the cheap flat-share you found has a very expensive exit clause.
- Low Japanese rates encourage borrowing in yen.
- Higher yields abroad attract that money into foreign assets.
- A rising yen or rising Japanese rates can force investors to unwind those positions.
- The unwind may pressure shares, bonds and currencies well outside Japan.
This is why policymakers and portfolio managers watch the yen not merely as a measure of Japan’s competitiveness, but as an indicator of global risk appetite.
Why US Treasury yields are part of the story
Japan’s role as an international investor adds another layer. Japanese institutions have long held large amounts of overseas debt, including US Treasuries. When yields abroad are attractive after allowing for currency-hedging costs, those holdings can make perfect sense. When conditions change, the calculation changes with them.
A government seeking to support its currency may sell foreign assets and use the proceeds to buy its own currency. The video’s analysis argues that yen-support measures and changes in Japanese demand for US bonds could matter for US borrowing costs. The mechanism is straightforward: if a major buyer reduces purchases or sells holdings, bond prices can fall and yields can rise.
That matters because US Treasury yields are a global reference point. They influence corporate financing, mortgage costs and the relative appeal of everything from German Bunds to emerging-market debt. A shift in Japanese flows will not single-handedly dictate the price of money everywhere—markets are much messier than that—but it can be a meaningful force when public debt issuance is already heavy and investors are nervous.
What yen volatility means for Europe
Europe is not a spectator in this drama. For euro-area exporters, currency changes alter competitive positioning in markets where Japanese companies are rivals, especially in cars, industrial equipment and precision manufacturing. A weaker yen can make Japanese goods cheaper abroad, putting pressure on European competitors. A stronger yen can reverse some of that advantage.
Financial links matter just as much. If a carry-trade unwind drives investors into safer assets, European stock markets can feel the chill, particularly sectors dependent on cheap funding or buoyant global demand. Bond markets may also react to movements in US yields, though the European Central Bank’s policy path and local fiscal outlook remain crucial in their own right.
For households and businesses, the effects are less cinematic but tangible:
- European firms buying Japanese components may face changing import costs.
- European travellers can find Japan either remarkably good value or suddenly less so.
- Japanese visitors to Europe gain purchasing power when the yen strengthens against the euro, potentially helping tourism, retail and hospitality.
- Investors with global funds may discover that currency exposure is doing more work than the carefully selected stocks inside them.
Tourism is a useful reminder that exchange rates redistribute spending rather than simply creating or destroying it. A cheap Japan may pull some European travellers eastward; a stronger yen may make European city breaks and luxury shopping more attractive to Japanese visitors. Hotels, airlines and restaurants notice these shifts long before they become a textbook chart.
What to watch next
The decisive questions are not only where the yen trades today, but what investors expect tomorrow. Watch the Bank of Japan’s language on inflation, wages and further rate moves. Watch the gap between Japanese and US interest rates. Watch whether volatility is orderly or whether it starts forcing highly leveraged positions out of the market.
It is also worth watching foreign-bond flows from Japanese investors and the response of other central banks. Currency intervention can buy time, but it rarely abolishes the economic forces behind an exchange rate. Interest-rate differentials, energy costs, growth prospects and investor confidence eventually demand their say.
The yen’s real importance lies in that intersection. It is a domestic price for Japanese families, a competitiveness tool for exporters, a funding engine for global investors and a potential pressure point for bond markets. When it moves quietly, few people notice. When it does not, the ripple can reach Europe with surprising speed.